Insurance Claims
Storm and hail claims, handled with you
Rain, hail, wind, fire, storm damage, vandalism, explosions and collapse can all entitle you to a settlement. We have a team of experienced insurance claim specialists who make sure your insurer covers the damage you actually have.
Chapter 01
Should you even file a claim after a storm?
Honestly, not always. A storm rolling through Tulsa that drops a small amount of hail or blows a few shingles off does not mean your insurance company is going to pay out for a complete roof replacement. Filing anyway can cost you more than it returns, and the claim stays on your record either way.
So the order matters. Always have a licensed contractor come out and inspect the property first, before a claim exists. That way you are making the decision with a real assessment in front of you rather than guessing from the driveway.
We will come out and do that inspection free, and we will tell you plainly if we think there is not a claim worth making. That answer is worth more to you than an optimistic one.
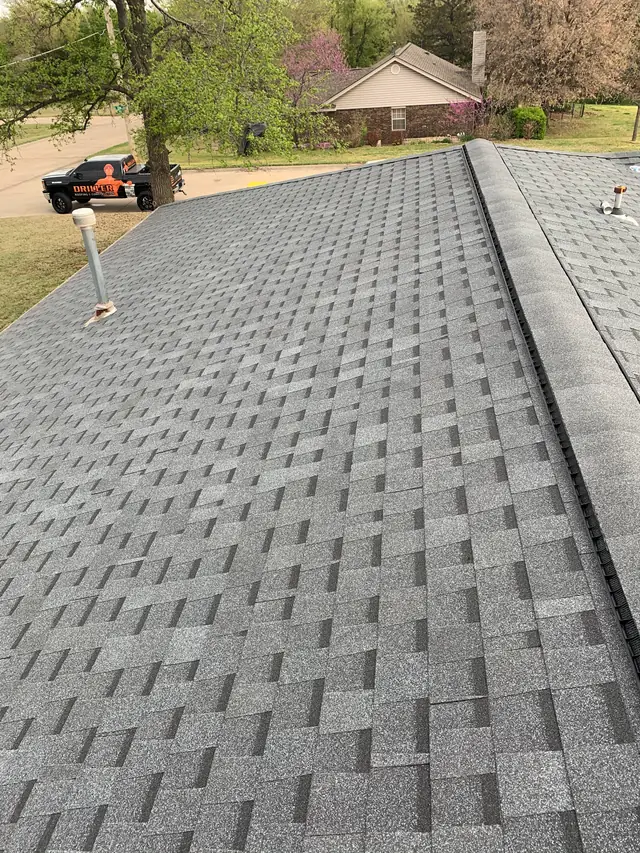
A Driller Roofing crew member on a roof laying fresh shingles, with the branded company truck on the street below
We mark the damage before the adjuster arrives
This is the part that separates a paid claim from an underpaid one. We go over the property first and physically mark every point of damage we find, on the roof and on everything else the storm touched, including doors, guttering and siding. Hail does not politely restrict itself to the roof, and those other items are routinely left off a settlement simply because nobody pointed at them.
Then we are there when the adjuster comes out, walking the same property with them, so that everyone is looking at the same marked damage at the same time. An adjuster working alone from a ladder sees what they see. An adjuster walking a marked property sees what is actually there.
One customer put it exactly this way: Driller came out, marked the roof and the doors that were damaged, and then came out again when the insurance company came so they made sure the damage was seen. That is the process, not a one off favour.
Chapter 03
Supplements, and what to do when the first answer is no
A first refusal is not the end of a claim, and it is not unusual. We go back with supplements, which means documenting the items the initial settlement missed or underpriced and putting them back in front of the insurer with evidence attached. We can also help you book an appointment with a supplemental process adjuster.
It works often enough that customers write about it. One homeowner had a claim turned down with the first company they called, and our team got the same roof approved. Another described us as fighting for them until the insurer finally approved the work. A third had a crew out to tarp the roof ahead of an incoming storm while the claim was still being argued, so the house was protected in the meantime.
The point of all of it is that you should not have to become an expert in your own policy to get the roof you are already insured for. Call the office on (918) 508-1771 and we will take it from the inspection onwards.
Driller Roofing. Fully bonded, licensed and insured. Oklahoma License #80003885. Atlas Certified Contractor. Call (918) 508-1771.